Retire at 55 Without One Diagnosis Erasing Decades of Work
You've built real wealth on a ₱150K–₱500K monthly income — but a single heart attack, stroke, or cancer diagnosis could drain your retirement fund before you ever use it. Let's close that gap, while we're still here.
No obligation · completely confidential · one focused conversation about your situation, not a product pitch.
Focus areas
Holistic Financial PlanningBusiness Owners & SMEsMedical & Healthcare ProfessionalsExecutives & C-suiteYou're Close to 55 — and One Diagnosis Away from Losing It
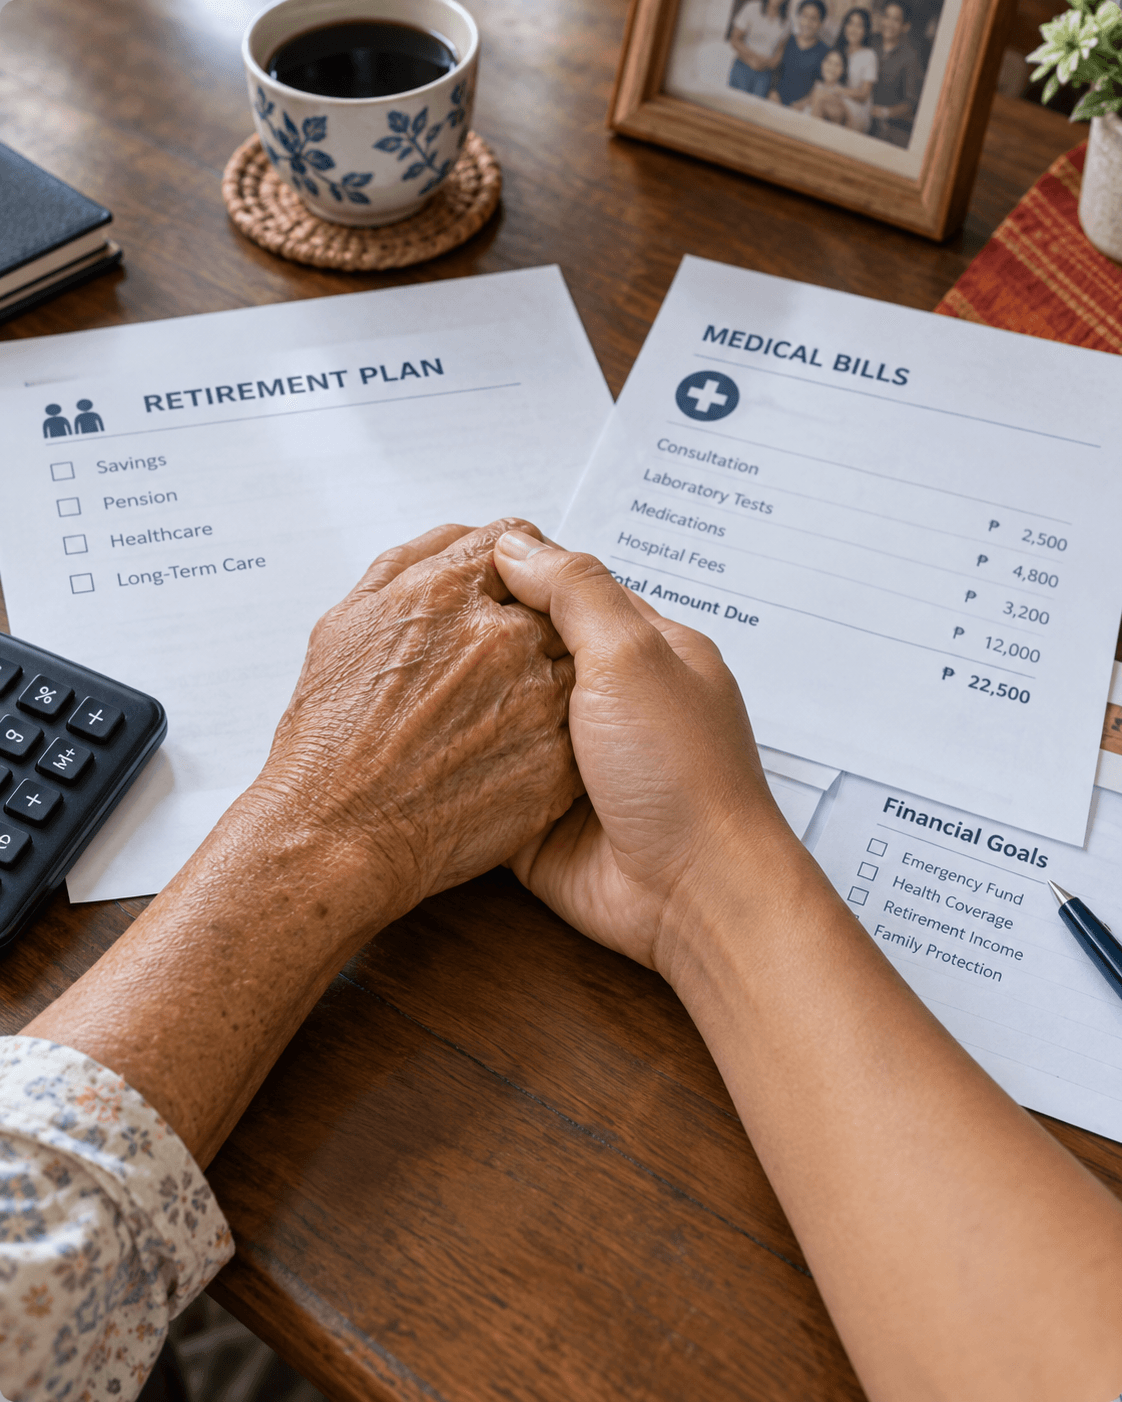
You've watched it happen to colleagues: a heart attack or stroke at 58, and what should have been retirement income is consumed by medical bills within months. They're back at work at 60, not by choice. You're earning well, saving consistently, and tracking toward early retirement — but if a critical illness strikes tomorrow, your family could be 3 to 5 months from financial crisis. That gap between what you've built and what you've protected is the vulnerability almost no one sees until it's too late.
Your ₱50K–₱100K Monthly Lifestyle Stays Intact — No Matter What
You'll know exactly which 5 financial protections must be in place now so that if critical illness strikes before or during early retirement, your monthly lifestyle continues without touching your retirement fund. Not a vague plan — a clear picture of what you already own, where the real gaps are, and what needs to change. Because you didn't work three decades to let one diagnosis undo all of it.
Critical Illness Before Retirement
We map exactly how a single diagnosis could impact your retirement fund — and which protections ensure your ₱50K–₱100K monthly lifestyle survives it. You'll retire at 55 on your terms, not on whatever is left after medical bills.
Policy Review, Not Sales Pitch
We start with what you already own: what works, what doesn't, and where the gaps are — so you decide from a place of clarity, not confusion. Understanding your protection comes first; strengthening it comes second.
The 3–5 Month Crisis Test
If you died, became critically ill, or were disabled tomorrow, how long could your family sustain their lifestyle without touching savings? We answer that question honestly — and build the income-replacement and emergency structure that closes the window.
Clarity First — Then the Right Protection
I became a financial advisor after living through what I now help families prevent. When my father got sick, and later when my mother was diagnosed with cancer, I watched emotional pain become heavier under financial stress. That experience is my purpose. I don't simply offer insurance policies — I help executives and medical practitioners understand what they truly own before recommending anything new. The carriers and licenses below reflect the credentials I've earned to do this work properly.
 Pru Life UKVariable · Life
Executives Who Finally Understand Their Protection
“When I adopted Joy's account, she owned several policies — but almost no meaningful critical illness coverage. Instead of recommending something new immediately, I sat with her and walked through every plan she already had: what worked, what didn't, and where the real risk sat. She told me afterward that for the first time, she truly understood her own policies. That clarity led her to protect her entire family — herself, her husband, and their daughter. That's the kind of work that gives my career real purpose.”
I Help Families Prepare — Not Just Buy a Policy
I work with executives, medical practitioners, and business owners in their 40s to mid-50s who've built real wealth but carry a hidden vulnerability: one critical illness could drain their retirement fund before they ever get to use it. What's different about how I work is that I start with what you already own — not to sell you something new, but to show you exactly where the gaps are. Clarity comes before any recommendation, because that's what allows you to focus on what truly matters instead of worrying about finances.
How I Think About Your Retirement Protection
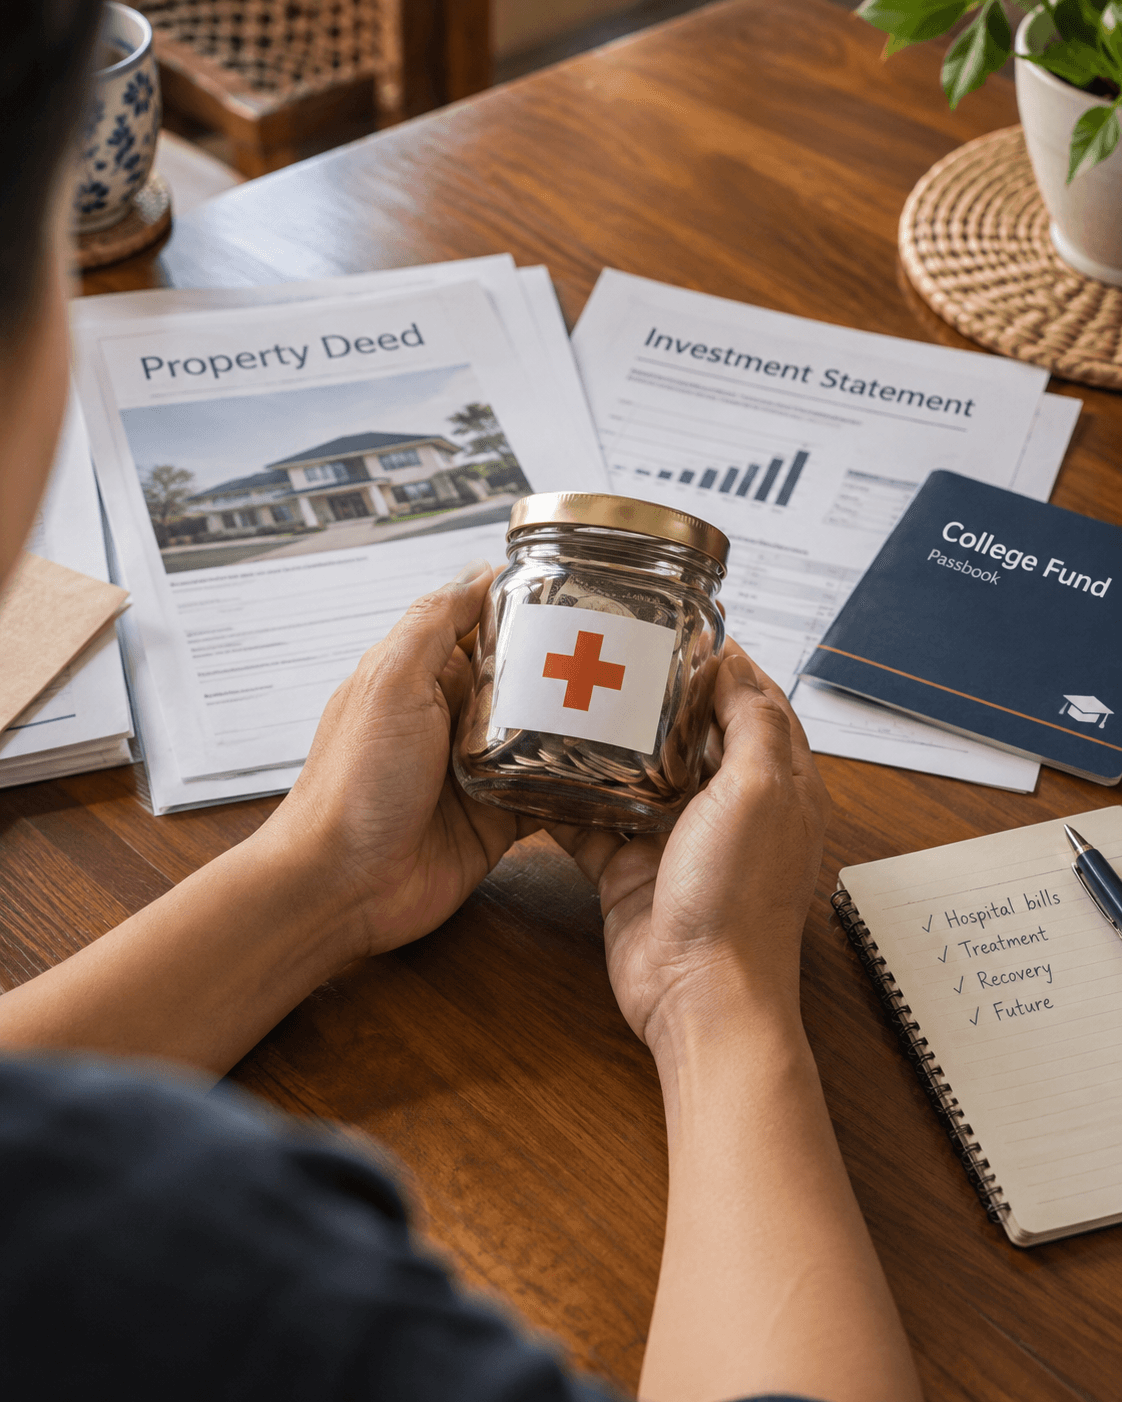
Start With What You Already Own
Free resources to help you understand your coverage before you change anything.
I already have insurance policies. Why do I need a review?
Owning policies and being properly protected are not the same thing. Many executives I meet have multiple plans but dangerously low critical illness coverage — a gap that only becomes visible when we map what they own against what their family would actually need. A review answers that question before a diagnosis does.
How is this different from a standard insurance consultation?
We begin with what you already own — not a product presentation. I walk through your existing plans to show you what works, what doesn't, and where the real risk sits. Only after that clarity do we discuss whether anything needs to change.
I'm in my late 40s — is it too late to fix the gaps?
It's not too late, but the window does narrow as you approach 55. Acting now means you still qualify for meaningful critical illness coverage at reasonable rates — and you'll retire knowing your fund is protected, not hoping it is.
What exactly are the 5 protections I need before I retire?
The specific five depend on what you already have in place, your monthly income level, and your retirement timeline — there's no single universal list. A discovery call is the right place to map this out against your actual situation.
What happens in the discovery call?
We spend the time understanding your current protection, your retirement goal, and the most urgent gaps. There's no sales pitch — you'll leave with a clearer picture of where you stand and what, if anything, needs attention. No obligation, completely confidential.
Book a Discovery Call
Find out exactly where your retirement protection stands — and what needs to change before 55.
Book a Discovery Call →No obligation · completely confidential · one focused conversation about your situation, not a product pitch.